The Hidden Perk - How Voluntary Group Benefits Can Add Value Without Direct Employer Premium Costs
Growth-with-Samuels-Insurance-Group
For small and mid-sized business owners, attracting and retaining good employees while managing payroll and operating costs can be a constant balancing act.
You want to take care of your employees. You want your benefits package to help you compete for talent. At the same time, adding another employer-paid benefit can mean another recurring expense.
So, what options are available if you want to give employees access to additional insurance protection without directly paying their premiums?
One option to consider is voluntary supplemental group benefits.
Under an employee-funded arrangement, employees can choose available coverage based on their individual needs and pay the applicable premiums. The employer provides access to the program without paying the direct insurance premium.
This approach can give employees more choices while allowing businesses to manage their benefits budget.
The Small Business Benefits Challenge
Large corporations may have dedicated HR departments and substantial budgets for employee benefits. Small and growing businesses often operate with different resources and priorities.
You may want to offer more to your employees, but every additional recurring expense affects the business.
Voluntary benefits can be one way to expand the options available to employees without adding employer-paid insurance premiums.
Rising Benefit Costs
Challenge: Employer-paid insurance can increase recurring business expenses.
Voluntary approach: Employees can choose whether to participate and pay the applicable premiums under an employee-funded arrangement.
Different Employee Needs
Challenge: Employees and their families have different financial needs and priorities.
Voluntary approach: Employees can select from available coverage based on their individual circumstances.
Limited HR Resources
Challenge: Small businesses may not have large HR or benefits departments.
Voluntary approach: A benefits partner may assist with education, enrollment, and implementation, depending on the arrangement.
Competing for Talent
Challenge: Smaller companies may compete with employers that have larger benefits budgets.
Voluntary approach: Voluntary benefits can expand the options available to employees without adding employer-paid insurance premiums.
The goal is not to imitate a large corporation's benefits package.
The goal is to determine what meaningful options you can responsibly make available to your people.
What Are Voluntary Supplemental Group Benefits?
Supplemental insurance is designed to complement, not replace, major medical health insurance.
Depending on the products available and the specific policy terms, employees may have access to coverage such as:
Critical Illness Coverage
Certain policies may provide benefits associated with covered conditions such as cancer, heart attack, or stroke.
Accident Coverage
Accident insurance may provide specified benefits following covered accidental injuries and related treatment.
Hospital and ICU Benefits
Depending on the policy, benefits may be available for covered hospitalizations, intensive care stays, or other qualifying events.
Life Insurance
Life insurance can provide financial protection for an insured's beneficiaries following a covered death, according to the terms of the policy.
Return of Premium Options
Certain qualifying policies may include a Return of Premium (ROP) provision.
Depending on the policy and its requirements, eligible premiums may be returned after a specified period when applicable conditions are satisfied.
Because provisions vary by policy, employees should always review the actual policy terms when evaluating coverage.
Why Supplemental Coverage Can Matter Even With Health Insurance
A common question is:
"Why would I need supplemental insurance if I already have health insurance?"
The two types of coverage are designed to address different needs.
Major medical insurance primarily helps with eligible healthcare expenses. However, when a serious illness or accident occurs, a family's everyday financial responsibilities do not disappear.
The mortgage or rent is still due.
Utilities still need to be paid.
Families still need groceries.
Children may still need childcare.
Transportation expenses continue.
Time away from work can also make everyday financial obligations more difficult.
Depending on the policy, certain supplemental insurance benefits may be paid directly to the insured following a covered event. That may provide additional financial flexibility when a family is dealing with an unexpected situation.
Think of supplemental insurance as another potential layer of financial protection, rather than a replacement for major medical coverage.
Leadership First. Insurance Second.
At Samuels Insurance Group, we believe a benefits conversation should begin with people, not products.
Our mission is:
To protect families while developing leaders who serve with integrity, grow with purpose, and create opportunities for others.
That mission is supported by four core values:
SERVICE | INTEGRITY | GROWTH | LEADERSHIP
These values influence how we believe businesses should approach employee benefits.
SERVICE | Start With the Employee
Service means putting people first and looking for opportunities to make a meaningful difference.
For a business owner, that starts with a simple question:
What can I make available to my employees that could genuinely help them and their families?
You cannot eliminate every financial challenge your employees may experience. You can, however, create access to resources that may help them prepare.
That's service.
INTEGRITY | Educate, Don't Sell Through Fear
Insurance should not have to be sold through fear.
Employees deserve to understand:
What the policy covers
What it does not cover
What it costs
Applicable limitations and exclusions
How benefits are paid
Whether participation makes sense for their individual situation
Employers deserve the same transparency about their responsibilities.
Our role should be to educate first.
Give people good information.
Answer their questions.
Then allow them to make an informed decision.
That's integrity.
GROWTH | Let Your Benefits Strategy Grow With Your Business
A five-person company operates differently from a 50-person company. A 50-person organization may have very different needs when it grows to 100 employees.
Your benefits strategy should be able to evolve with your business.
That does not mean adding every possible benefit. It means periodically asking:
Are the benefits we offer today appropriate for the company we are becoming?
Growth begins by understanding where you are, identifying potential gaps, and determining the next responsible step.
LEADERSHIP | Create Opportunity and Access
Leadership does not always mean paying for everything.
Sometimes leadership means creating access.
You provide the opportunity.
You provide education.
You give employees choices.
Then you allow your people to determine what is appropriate for their families.
At Samuels Insurance Group, we believe leadership means taking ownership, leading by example, and developing others. A thoughtful employee benefits strategy can be one way a business owner puts that philosophy into practice.
Employer-Funded vs. Employee-Funded Benefits
Employer-Funded Benefits
Who pays?
The employer pays some or all of the premium.
Business impact:
This creates a direct insurance premium expense for the business.
Cost structure:
Recurring benefits expenses can increase as the organization grows.
Voluntary Employee-Funded Benefits
Who pays?
Participating employees pay the applicable premiums.
Business impact:
The employer provides access without paying the direct insurance premium under an employee-funded arrangement.
Employee choice:
Employees can choose among available voluntary options based on their individual needs.
Cost structure:
Voluntary benefits can expand available benefit options while preserving the employer's benefits budget.
It is important to understand that voluntary does not necessarily mean there are no responsibilities for the employer.
There may be enrollment, payroll, eligibility, administrative, or other considerations depending on the program.
That is why it is important to understand the complete arrangement before implementing it.
Integrity requires clarity.
What Could Voluntary Benefits Do for Your Business?
For the right organization, voluntary supplemental benefits may help you:
Expand your benefits offering without adding employer-paid insurance premiums
Give employees more choices based on their individual circumstances
Enhance your employee value proposition when recruiting and retaining talent
Provide access to additional financial protection for employees and their families
Build a benefits strategy that can evolve as your organization grows
Most importantly, you are giving employees something valuable:
Choice.
You are not deciding what every family needs. You are creating access, providing education, and allowing employees to make that decision for themselves.
Frequently Asked Questions
Can a Small Business Offer Employee Benefits Without Paying the Insurance Premiums?
Certain voluntary benefits can be structured as employee-funded coverage.
Participating employees pay their applicable premiums while the employer provides access to the program.
Employer responsibilities can vary depending on the benefit and arrangement.
What Are Voluntary Employee Benefits?
Voluntary benefits are optional benefits employees can choose to participate in. Depending on the program, employees may pay some or all of the applicable premium.
Does Supplemental Insurance Replace Health Insurance?
No.
Supplemental insurance is designed to complement, not replace, major medical health insurance.
The specific benefits depend on the policy selected.
What Supplemental Insurance Can a Business Offer Employees?
Depending on availability, eligibility, jurisdiction, and the insurance provider, options may include:
Accident insurance
Cancer coverage
Heart or stroke coverage
Hospital or intensive care-related coverage
Life insurance
Other supplemental products
Why Offer Supplemental Insurance if Employees Already Have Health Insurance?
Health insurance and supplemental insurance serve different purposes.
Major medical insurance primarily helps with eligible healthcare expenses, while certain supplemental policies may provide specified benefits following covered events.
Who Pays for Voluntary Supplemental Insurance?
Under an employee-funded arrangement, participating employees generally pay their applicable premiums.
Other arrangements may involve employer contributions.
Start With a Benefits Review, Not Another Expense
You do not need a large corporate benefits budget to give your employees meaningful choices.
You also do not need to decide immediately that your company needs another insurance product.
Start by understanding what you already have.
At Samuels Insurance Group, we help small and mid-sized businesses:
Review current benefits
Identify potential coverage gaps
Explore available voluntary supplemental insurance options
Educate employees about their choices
Implement an enrollment strategy appropriate for the organization
A benefits review can help you understand what is possible before deciding what is appropriate for your company.
Because taking care of your people is not simply an HR function.
It's leadership.
Protect Families. Develop Leaders. Build Legacies.
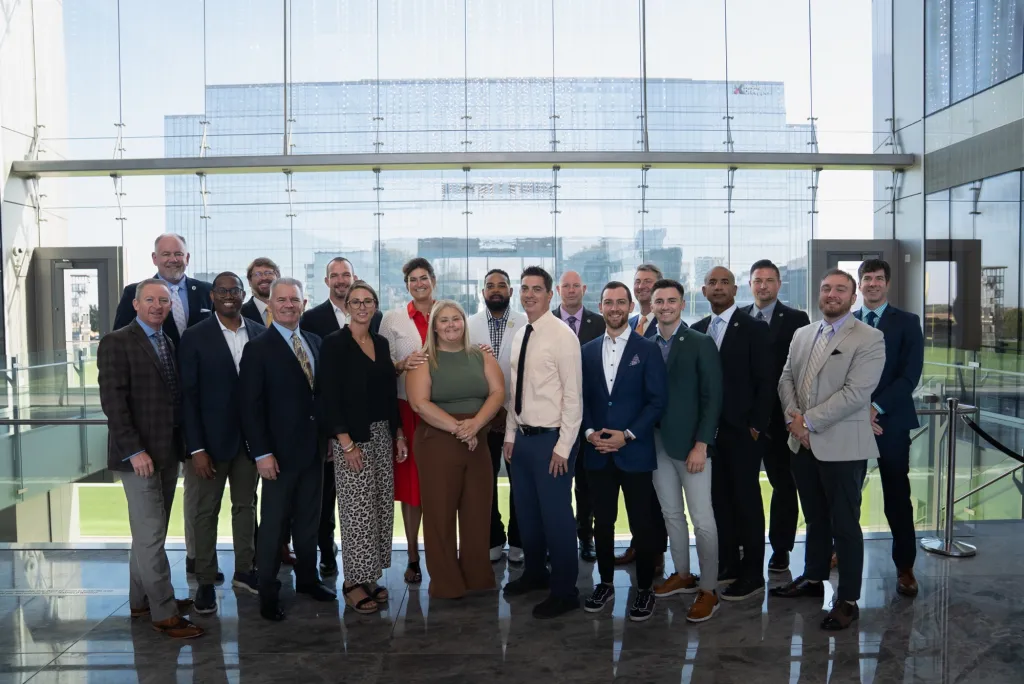
Our vision at Samuels Insurance Group is:
To impact and improve the lives of people for generations to come.
For employers, that can start with creating better opportunities for the people who help build your business every day.
SERVICE | INTEGRITY | GROWTH | LEADERSHIP
Ready to Review Your Benefits?
A benefits review can help you understand whether voluntary supplemental benefits could expand the options available to your employees without adding direct insurance premium costs to your business.
At Samuels Insurance Group, our goal is to help you understand your options, identify potential gaps, and determine what makes sense for your business and your people.
Request a Group Benefits Review
Disclaimer
Insurance products, benefits, eligibility, exclusions, limitations, premium-return provisions, employer responsibilities, and availability vary by policy, program, carrier, and jurisdiction. This article is provided for general educational purposes and does not represent that any specific product, feature, or program is available to or appropriate for every employer or individual. Career opportunities, licensing requirements, compensation, eligibility, and availability vary by position and jurisdiction. Pasted markdown
Patrick B. Samuels
Patrick B. Samuels is a Dallas, Texas native and Regional Director at Samuels Insurance Group. A Texas State University alumnus, he has worked in the supplemental health insurance industry since 2015, with a focus on leadership, team development, professional growth, and mentorship.
Executive Insights & Reader Discussion
Share your perspective on supplemental risk protection, agency leadership, and market trends.
Discussion (0)